
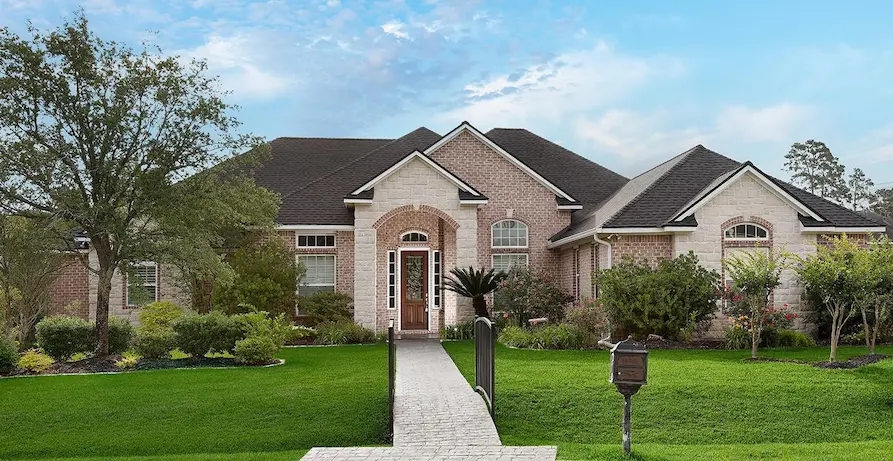
Buying a home breaks down into 13 key steps, from budgeting and mortgage pre-approval through house hunting, offers, inspection, and closing. A useful rule of thumb: keep your housing payment at or below roughly 28% of your gross monthly income. That keeps you within a lender’s comfort zone before you even start browsing listings.
Purchasing a residential property means lining up financing, touring communities, and closing with the right guidance at each stage. AOT supports Texas buyers from starter homes to luxury estates, drawing on market knowledge across the residential market. With the right team in place, financing decisions, home tours, offer negotiations, and closing paperwork stop feeling like separate hurdles and start working as one coordinated process toward homeownership.
Get Your Finances and Paperwork in Order First
Good preparation is what makes the home buying process feel manageable instead of stressful. Marine CU calls buying a home one of life’s biggest milestones, and a decision that size rewards careful groundwork over rushed action. Skipping preparation can cost buyers negotiating power, delay closings, and open the door to financing surprises that derail an otherwise strong offer.
Financial readiness comes first. The Homebuying Process for First-Time Homebuyers recommends confirming mortgage preparedness before searching begins, not after falling for a listing. That means reviewing credit standing, calculating a realistic budget, and gathering the documentation lenders will ask for.
Documents to Gather Before You Start Searching
Organizing paperwork early beats scrambling once an offer deadline hits. A prepared file typically includes:
- Recent pay stubs and tax returns for income verification
- Bank statements showing available funds for a down payment
- Credit reports to identify and correct errors before applying
- A pre-approval letter confirming borrowing capacity
A Proven Local Track Record Adds Weight
Preparation alone doesn’t guarantee a winning offer in competitive Texas markets. AOT has closed more than $1 billion in transactions and sold over 5,000 properties across Texas, a record that informs the pricing strategy and negotiating guidance buyers receive from day one.
Prepared buyers move faster once the right property appears. Pairing solid financial footing with experienced guidance turns preparation into a real competitive advantage, not just a checklist to complete.
Set a Realistic Budget and Get Pre-Approved
A workable budget is the foundation of any residential property buying process in Texas. Skipping this step often leads to overspending, mortgage denial, or a rushed decision made under pressure. Buyers who calculate affordability first negotiate offers with confidence instead of guesswork.
Building the budget starts with math, not a wish list. Add up total monthly take-home pay, then subtract every fixed non-housing expense: car payments, student loans, insurance, groceries. What’s left signals the monthly housing payment a buyer can sustain without financial strain.
- Total monthly take-home income across all household earners.
- List and subtract fixed monthly expenses, including debt payments and insurance.
- Set a target down payment based on loan type and purchase price.
- Apply for mortgage pre-approval to confirm borrowing power in writing.
- Bring the pre-approval and budget to AOT for pricing guidance before touring homes.
Down Payment Minimums Vary by Loan Type
Down payment amounts shift depending on loan type; there’s no single fixed rule. Conventional loans sometimes require as little as 3% of the purchase price, which lowers the upfront cash barrier for qualified buyers. Buyers should confirm minimums with their lender before assuming a specific percentage applies to their situation.
Pre-approval turns a budget into buying power. AOT applies pricing strategy grounded in local sales data to help buyers understand true property value against their approved loan amount, so offers reflect real market conditions rather than sticker price alone. That approach carries buyers from spreadsheet math to a confident, competitive offer, backed by knowledge of Texas communities like Conroe and The Woodlands.
Find a Neighborhood That Actually Fits Your Life
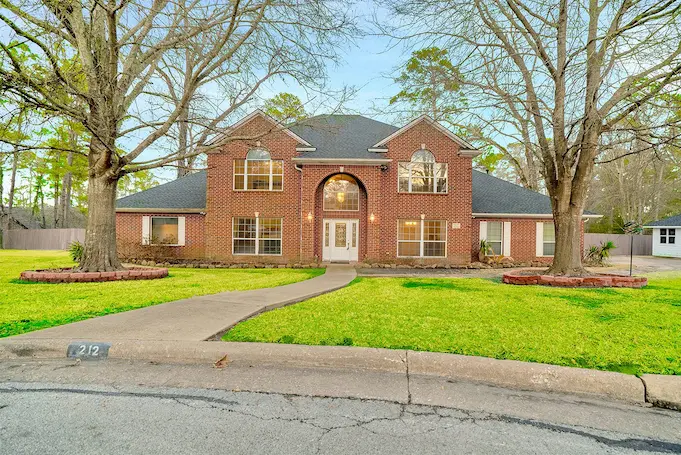
Neighborhood selection matters more for long-term satisfaction than almost any other decision buyers make. Four factors stand out most: commute distance, budget ceiling, preferred pace of life, and tolerance for ongoing construction and development. Buyers who weigh these factors early are less likely to run into a costly resale mismatch down the road.
AOT’s residential coverage spans starter homes to luxury estates across Texas communities, giving buyers options at every price point and life stage. That range matters because a young family’s priorities rarely match those of a retiree or a first-time investor. Matching home type to life stage, not just square footage, generally leads to a decision buyers are still happy with years later.
Montgomery County, including Conroe, ranks among the fastest-growing parts of the Houston metropolitan area. Rapid growth brings new schools, retail, and infrastructure, but it also means construction noise and shifting traffic patterns for a few years. Buyers should weigh that trade-off when shortlisting neighborhoods.
Factors Worth Comparing Before You Commit to an Area
Prioritize these factors before narrowing a list of candidate neighborhoods:
- Commute time to work, school, and regular errands
- Budget alignment, including property taxes and HOA fees
- Pace of life, from quiet suburban streets to active town centers
- Development tolerance, since growing areas mean ongoing construction
Local Presence Sharpens Neighborhood Insight
Local grounding shortens the learning curve for buyers unfamiliar with an area’s microneighborhoods. AOT operates from Huntsville, Texas, giving clients a locally rooted resource for street-level, area-specific guidance instead of generic advice. That proximity often translates into sharper insight on which blocks hold value and which are still finding their footing.
Make a Winning Offer and Get to the Closing Table
Making an offer means putting together a written proposal backed by financing proof, then moving through negotiation, inspection, and a final signing at the closing table. Skipping expert guidance at this stage can cost buyers leverage during negotiations and time during closing. AOT clients work with a dedicated team of contract experts and a trusted vendor network built for the offer-to-close stage.
The steps to buy a house narrow sharply once a buyer identifies the right home. Decisions made in these final weeks determine the final price, the repair credits secured, and the closing date itself. Follow these steps in order:
- Submit a written offer that includes price, contingencies, and a proposed closing timeline.
- Negotiate terms with the seller, adjusting price or concessions as needed.
- Schedule a home inspection and review findings before waiving contingencies.
- Finalize mortgage approval with a lender or personal banker.
- Secure a homeowners insurance policy ahead of closing.
- Review closing disclosures and confirm all figures match the agreed contract.
- Sign closing documents and transfer funds to complete the sale.
The Professionals Who Guide You Through Offer and Closing
Real estate agents, personal bankers, mortgage brokers, and insurance agents each play a distinct role in guiding sound offer and closing decisions. A buyer working alone risks missing contract details or insurance gaps that surface only after signing.
How AOT Keeps Small Issues From Becoming Big Ones
AOT’s contract experts and vendor network review paperwork at this stage, drawing on deep closing experience across Texas. A team with that much experience is quick to catch small issues before they turn into delays.
Steer Clear of the Mistakes That Sink Deals Before Closing
Financial instability is one of the more common reasons closings fall apart in the final stretch. Marine CU’s research on first-time buyers points to a clear pattern: once the home buying process begins in earnest, buyers should avoid changing jobs, opening new credit accounts, or making large cash purchases. A lender re-checks credit and income before closing, and any disruption puts the deal at risk.
Avoid these specific actions between contract signing and closing day:
- Switching employers or changing pay structure
- Applying for auto loans, credit cards, or other financing
- Making large, undocumented cash purchases or deposits
- Co-signing loans for another person
- Opening new lines of credit, even store cards
Careful Paperwork Review Heads Off Deal-Breaking Errors
Contract experts and a trusted vendor network review paperwork line by line, spotting issues buyers often miss on their own. This layered oversight helps protect the transaction when deadlines tighten and stakes rise.
Staying Informed Through the Final Stretch
Staying connected to market activity and listing updates keeps buyers prepared for last-minute changes. AOT’s marketing reach, which generates over 2 million monthly social media impressions, helps keep buyers informed and connected to available options right up through closing. That visibility matters when timelines shift or a backup plan becomes necessary.
Preparation remains the strongest defense against closing-day surprises. With self-education, sound planning, and steady discipline, buyers can move through this stage without the last-minute scramble that trips up so many transactions.
Talk to AOT Before You Start Touring Homes
Buying a residential property comes down to preparation, the right budget, a neighborhood that fits your life, and a team that can carry you through the offer and closing without missteps. AOT brings that same track record and market knowledge to buyers working the Conroe, The Woodlands, and Huntsville markets.
Every stage of the home buying process, from the first budget conversation to the closing table, gets easier with a team that knows the market and can show the numbers to prove it. That same track record is there the moment you decide to start looking.
There’s no perfect time to buy a home, only a well-prepared one. Reach out to AOT today and take the next step toward owning it.
Frequently Asked Questions
How many steps make up the process of buying a residential property?
Homeownership follows 13 key steps, covering budgeting and mortgage pre-approval through house hunting, offers, inspection, and closing on a new home.
What is the 28% guideline for home affordability?
The 28% guideline limits a buyer’s housing payment to roughly 28% of gross monthly income, keeping costs within a lender’s comfort zone before searching listings.
What documents should buyers gather before starting their home search?
A prepared file includes recent pay stubs and tax returns, bank statements showing down payment funds, credit reports, and a pre-approval letter confirming borrowing capacity.

